When government bonds offered very little return, investors had to look elsewhere. Equities, real estate, private credit, private equity and other investments became increasingly important for those looking for higher returns.
Today, that conversation looks different. U.S. Treasury yields have moved above 5% across most maturities, a level we have not seen consistently for years. And I think this raises an interesting question for investors.
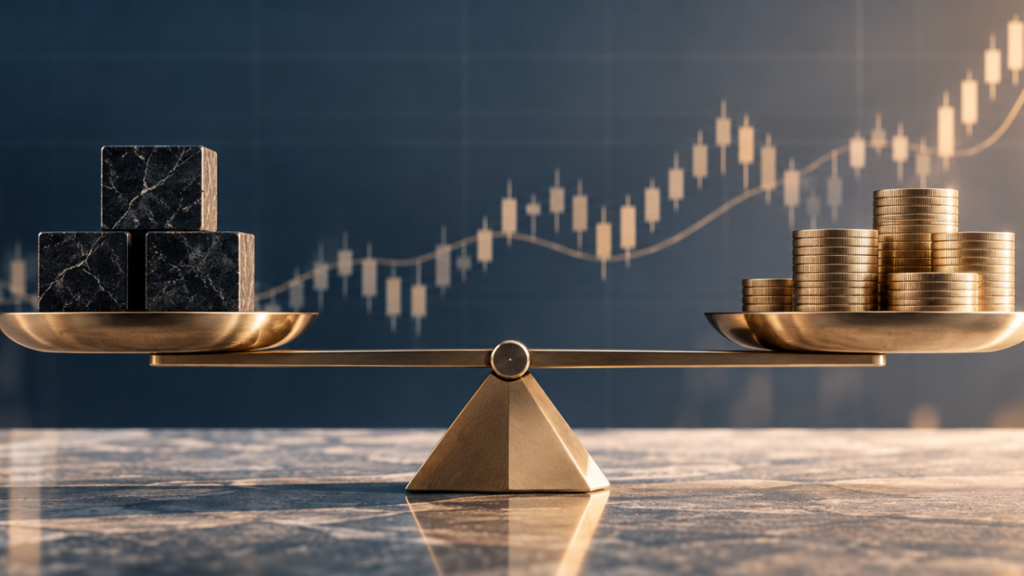
If relatively low-risk government debt can offer a meaningful return, how much additional return should you expect before taking additional risk?
An investment offering an expected return of 8% may look attractive on its own. But 8% means something very different when government bonds yield 1% than when they yield around 5%.
The difference is what you are being compensated for taking additional risk. That additional risk could be credit risk, market risk, illiquidity, leverage or simply having your capital committed for several years.
This becomes particularly relevant in private wealth, where investors often have access to a much broader range of opportunities, including private credit, private equity, real estate and structured investments.
It does not mean that these investments are suddenly less attractive. Many may still play an important role in a portfolio.
But the comparison has changed.
Perhaps the question is no longer simply:
“What return can I make?”
But:
“Is the additional return enough for the additional risk I am taking?”
And when the risk-free rate changes significantly, that is a question worth asking again.
Originally published by Paulina Cervera Taboada on LinkedIn.